


Professor Harvey Wainer’s forensic assessment disputes Council’s ‘no deficit’ defence and adds to concerns raised by ISS over Wellness Fund accounting.
A second independent analysis has challenged the National Bargaining Council for the Road Freight and Logistics Industry’s (NBCRFLI) response to concerns raised by Innovative Staffing Solutions (ISS) over R2.59 billion in worker benefit funds, finding that the Council’s claims are inconsistent with its own financial records.
Prepared by Professor Harvey Wainer of the Wits University School of Accountancy, an independent forensic accountant, the assessment reviews the Council’s response point by point. He concludes that several assertions are contradicted by the Council’s own documents, describing the media statement as “replete with clearly false and misleading statements”.
One central dispute surrounds questions raised by ISS over apparent deficits in the Sick Pay, Holiday Pay, and Leave Pay funds between 2021 and 2023. The Council rejected those concerns, emphasising there was “No Combined Shortfall” and that the three funds were not in deficit.
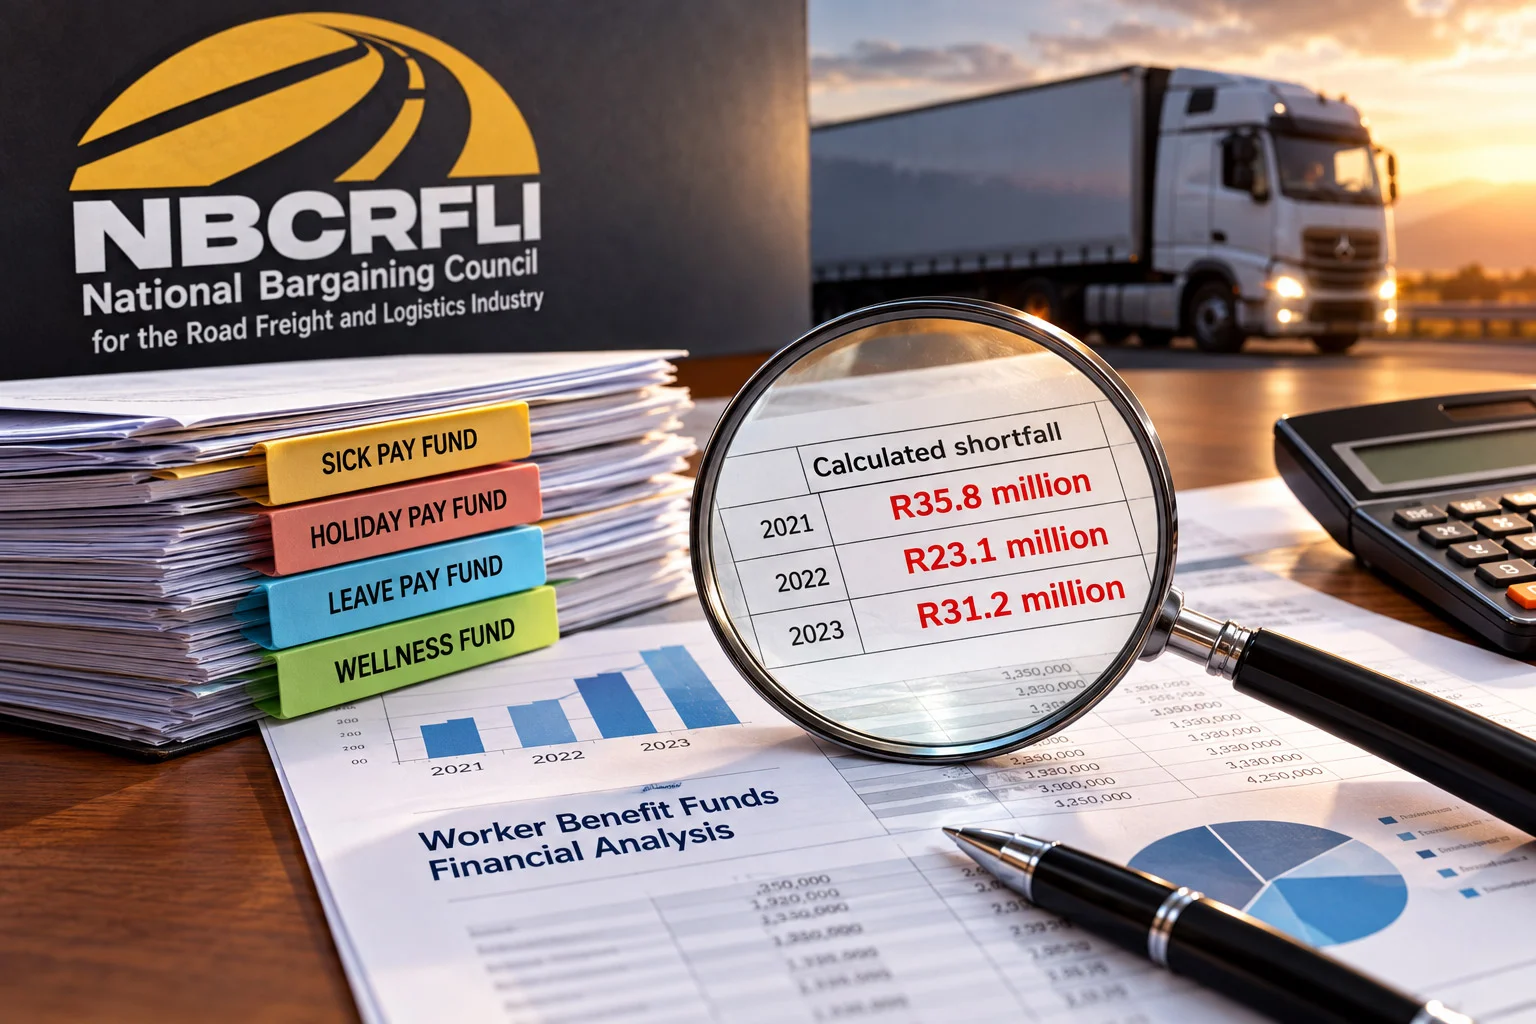
However, Wainer’s analysis says the Council’s own published figures do not support that response. Using only investments specifically identified as belonging to the funds, the analysis compares them with the aggregate liability recorded for those funds. It calculates shortfalls of R35.8 million in 2021, R23.1 million in 2022 and R31.2 million in 2023.
Table: Calculated Sick, Holiday, and Leave Pay Fund shortfalls, 2021-2023
Source: Professor Harvey Wainer, forensic analysis based on NBCRFLI audited financial statements
If other assets existed that offset or eliminated the shortfalls, Wainer argues those assets should appear in the financial statements as belonging to the funds. But the published accounts do not identify them. That means either the shortfalls remain, based on the figures disclosed by the Council, or additional fund assets were left out of the fund disclosures. Wainer notes that could amount to material non-disclosure.
ISS Managing Director Arnoux Maré stresses that this is a discrepancy the Council urgently needs to explain. “If there were enough assets to cover the obligations in each of the funds, the Council needs to show where those assets appear and how they are allocated. Workers should not have to guess,” he says.
Wainer’s analysis also rebuts the Council’s assertion that there is “no legal requirement” for separate fund financial statements. He cites the Main Collective Agreement, which requires a registered auditor for “each benefit fund” to audit its accounts and prepare a statement of money received and expenditure, together with a balance sheet of its assets and liabilities. These must be available for inspection and provided to the Registrar of Labour Relations.
Wellness Fund claims clash with Council’s accounts
ISS had previously questioned why Wellness Fund contributions appeared to be treated as Council revenue. The Council rejected that interpretation, stating the contributions “are not treated as Council revenue”. But Wainer’s analysis says the Council’s own financial statements prove otherwise, recording the contributions as revenue and showing them as the largest reported revenue component.
An even bigger issue, Wainer argues, is what happens to that money once it is recorded as Council revenue. Because reported revenue funds operating expenditure, the accounts indicate that Wellness Fund contributions may also be helping to finance the Council’s operations. This goes beyond the Council’s acknowledgement that investment income from worker funds is used for operational expenditure.
“That is a fundamental distinction. Workers deserve a clear answer on whether contributions collected for their wellness benefits are being used to meet the Council’s operating costs,” adds Maré.
Fundamental flaw in Council’s accounting defence
The accounting framework used by the Council was another issue previously flagged by ISS, and Wainer’s assessment now adds independent weight to that concern.
The Council uses the International Financial Reporting Standard for Small and Medium-sized Entities (IFRS for SMEs), but that standard is not intended for entities with “public accountability”. Wainer notes the Council falls within that definition because it administers billions of rand in worker benefit funds in a fiduciary capacity.
He further alleges that, even if IFRS for SMEs were appropriate, the Council’s statements do not comply with it in several significant ways. The analysis argues that the treatment of benefit fund assets and Wellness Fund contributions overstates the Council’s assets and revenue, while the absence of a corresponding Wellness Fund liability overstates its reserves.
“What makes this alarming is what it could mean for the financial picture presented to workers and the industry. If this latest analysis is correct, the Council may appear financially stronger on paper than it really is, while the true position of the worker benefit funds remains unclear,” says Maré.
“We again challenge the Council to publish fund-specific audited statements and balance sheets in line with its Constitution and Main Collective Agreement, and for the Registrar of Labour Relations and the Department of Employment and Labour to ensure the applicable reporting and governance requirements are being met.
“Workers need to know that money collected for their benefit is properly accounted for, protected, and available when they are entitled to it.”